The money matters less than people assume. The predictability matters far more.
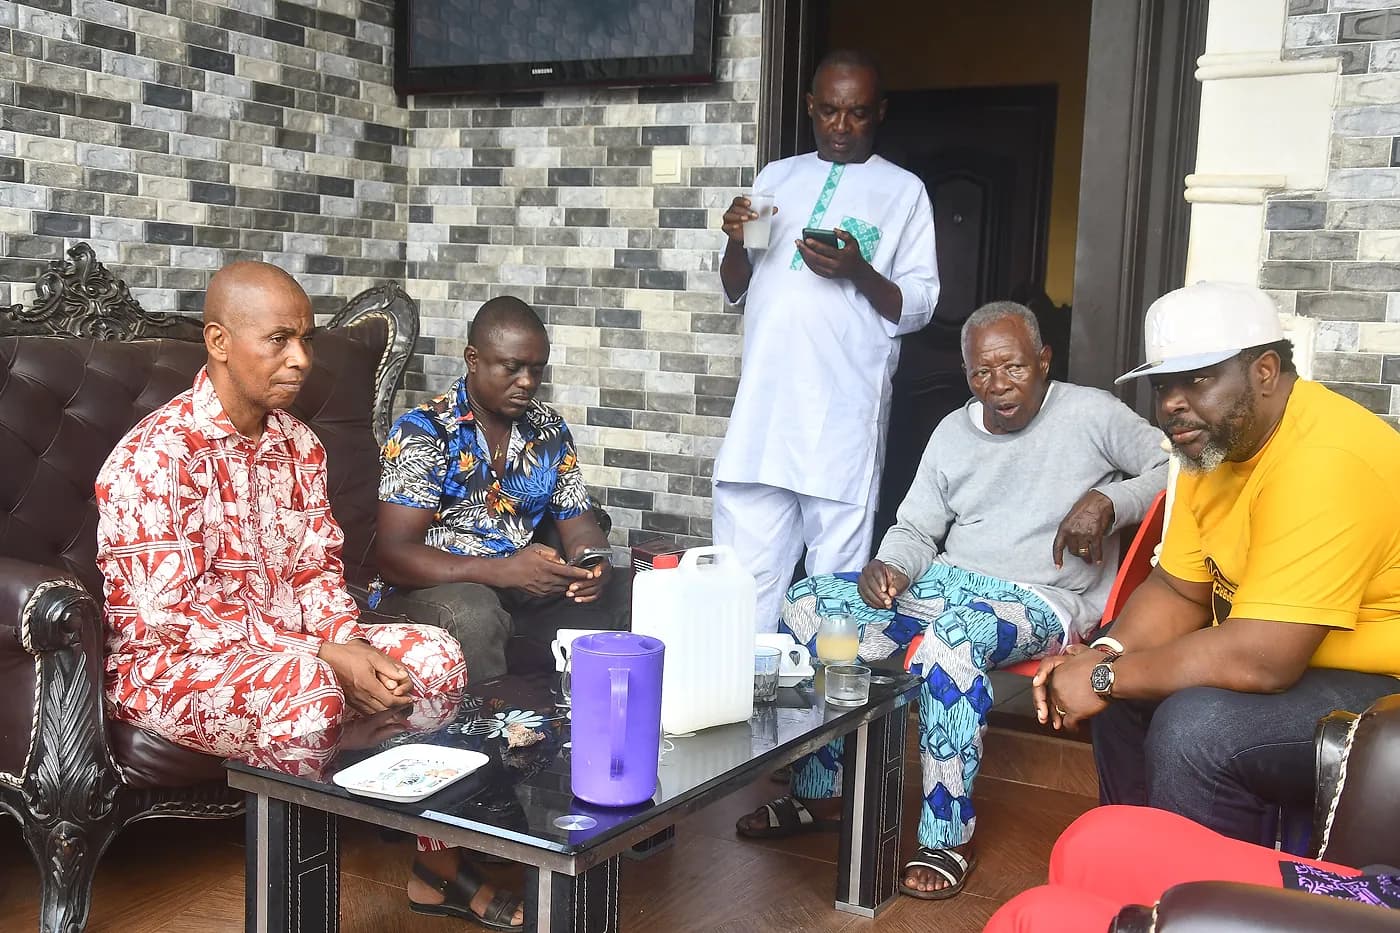
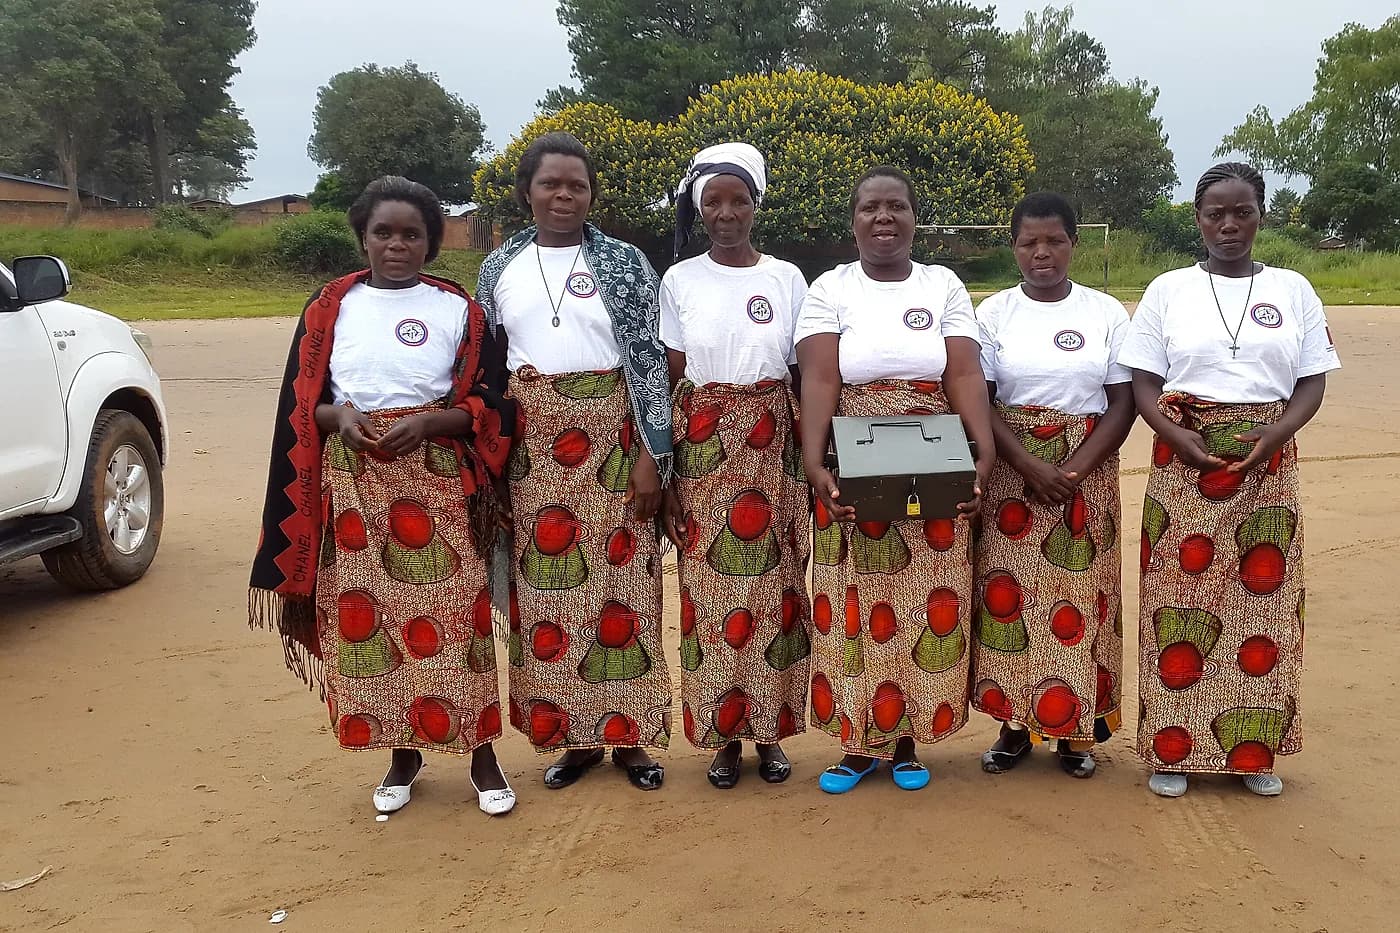
A community savings group is an unremarkable thing to look at. A dozen or so members, a locked box, a ledger, and a meeting that happens on the same day every week. The sums involved are small. The mechanism is old.
Its value is not primarily the capital it accumulates. It is that it converts an unpredictable financial life into a predictable one. A household that knows it can access a modest sum at a known time can make decisions it otherwise could not: pay school fees before the deadline, restock a stall before the market day, treat an illness before it becomes an emergency.
Why the group form matters
The group structure does work that an individual account cannot. It creates social accountability for saving, it distributes risk, and it puts financial decision-making in a room where it can be discussed — often the first time some members have had that.
- Regular, small deposits are easier to sustain than occasional large ones.
- Lending decisions are made by people who know the borrower’s circumstances.
- The group becomes a route for training, information and collective bargaining.
- Records are kept publicly, which builds the habit of financial transparency.
Verified quote from an LAHDI beneficiary or community partner. — to be supplied and verified by LAHDI.
No testimonial has been invented for this placeholder.
Savings groups are not a substitute for formal financial inclusion, and they do not resolve structural poverty. What they do is give a household a floor, and a floor is what makes planning possible.